All Categories
Featured
Why Senior Accident Coverage Protects Wealth
Table of Contents
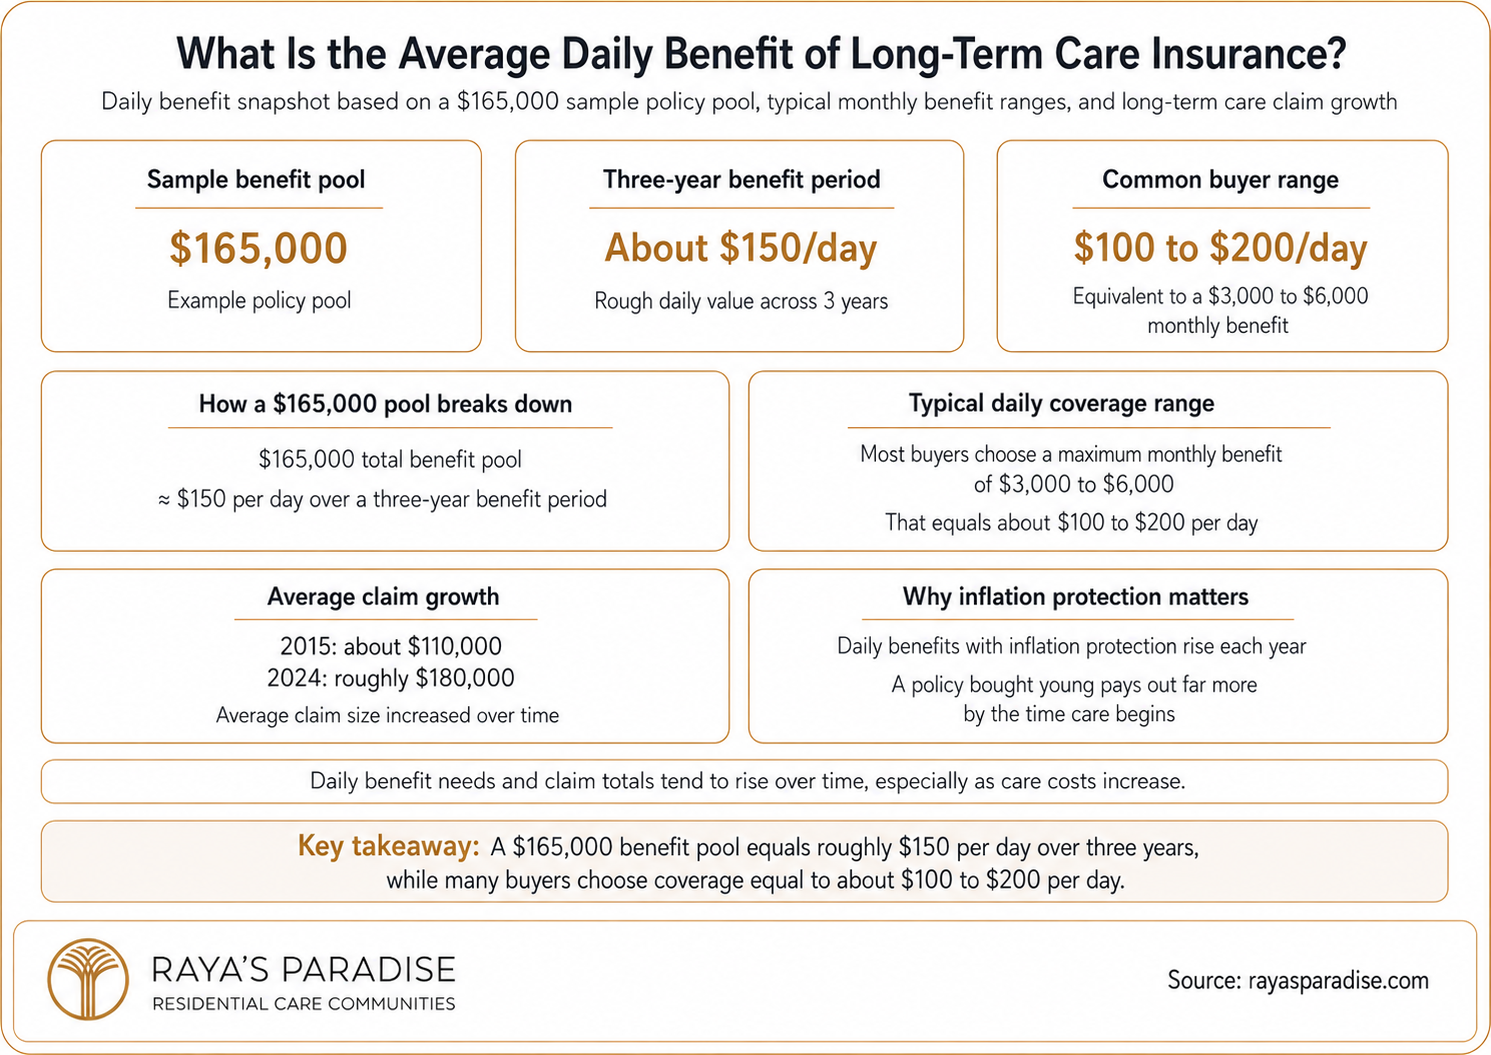
Data source: American Association for Long-Term Care Insurance Coverage (AALTCI) 2026 Price Index assessing leading U.S. LTC underwriters (insurance provider) throughout select age standards (55, 60, 65) for single men/women along with married couples/partners. 2026 AALTCI Long-Term Care Insurance Price IndexUpdated July 2026 COUPLE BOTH AGE 55: - According to the 2026 AALTCI Long-Term Care Insurance Coverage Price Index, the typical annual premium for a 55-year-old couple (both) acquiring $165,000 in preliminary benefits is $5,010 (integrated cost for both).
SINGLE WOMAN AGE 60: - According to the 2026 AALTCI Long-Term Care Insurance Coverage Price Index, the average annual premium for a 60-year-old lady purchasing $165,000 in initial benefits is $4,450. In 2025, the expected expense reported was $4,550. For 2026, AALTCI reports that the spread between the most affordable and the highest carrier rates for the exact same profile varies by up to 29%.
The policy consists of a 3% compound growth option - so that advantages increase by 3% yearly. The 2026 spread in between the most affordable and the greatest provider rate for the exact same profile differs by up to 80%. The following are real long-lasting care insurance coverage policy costs for an Illinois couple who are both AGE 60.
Understanding Variable Annuities Explained
Costs will vary by state and will depend upon each person's health at the time of application. Business 1: $4,591-per-yearCompany 2: $5,661-per-yearCompany 3: $6,440-per-yearCompany 4: $6,712-per-yearCompany 5: $7,173-per-yearIndividuals who PURCHASE THE THE MAJORITY OF pricey long-lasting care insurance coverage will PAY 56.24% MORE each year for essentially similar protection. This is why the Association advises working with an independent long-term care insurance expert who can compare policies from several insurance coverage business.

2026 rates are based on comparisons conducted by the American Association for Long-Term Care Insurance (July 2026). The initial policy advantage equivalent $165,000 for an individual with some health issues. Lower rates may be offered applicants in excellent health. Single Male, Age 55 (Select Health) $165,000 level advantages $ 950 Single Male, Age 55 (Select Health) benefits grow at 3% annual $ 2,200 Single Male, Age 55 (Select Health) benefits grow at 5% annual $ 3,710 Single Female, Age 55 (Select Health) $165,000 level advantages $ 1,500 Single Female, Age 55 (Select Health) advantages grow at 3% annual $ 3,750 Single Female, Age 55 (Select Health) advantages grow at 5% yearly $ 6,400 Couple Both Age 55 (Select Health) $165,000 level advantages $ 2,080 integrated Couple Both Age 55 (Select Health) advantages grow at 3% yearly $ 5,050 integrated Couple Both Age 55 (Select Health) benefits grow at 5% yearly $ 8,575 integrated Rates above are for an initial pool of benefits equal to $165,000.
Today, it's wise to think about both standard as well as linked-benefit long-lasting care insurance coverage. Numerous consumers being used a linked-benefit LTC insurance policy incorrectly think they cost about the very same as a standard long-lasting care insurance coverage policy.
Individuals do find features of linked-benefit policies appealing. They like the ability for recipients to get a death advantage if long-term care is not needed. However the added advantage (function) does feature a cost. Linked-benefit items today differ substantially and it is essentially difficult to offer an "apples-to-apples" comparison with standard long-lasting care insurance coverage policies.
According to AALTCI, in 2026 a traditional LTC insurance coverage that provides $180,000 of possible LTC benefits can cost a male who is age 55, about $1,050-a-year. Compare that to a connected advantage policy that supplies a $180,000 swimming pool of long-term care benefits as well as a minimum survivor benefit of ($120,000).
How Seniors Benefit From Critical Illness Plans
Policy cost contrasts carried out July 2026 and subject to change. NO INFLATION DEVELOPMENT - Cost Shown Equals YEARLY PREMIUMS Single Male, Age 55 - Swimming Pool of LTC Benefits = $180,000 Expense: $1,050 Single Female, Age 55 - Pool of LTC Advantages = $180,000 Expense: $1,645 Business A: Cost Shown Equates To YEARLY PREMIUM PAYMENTS Single Male, Age 55 - Pool of LTC Benefits = $180,000/ Minutes.
death advantage = $120,000 Cost: $3,265 Company B: Expense Revealed Equates To YEARLY PREMIUM PAYMENTS Single Male, Age 55 - Swimming Pool of LTC Benefits = $240,000/ Minutes. survivor benefit = $120,000 Cost: $3,750 Single Female, Age 55 - Pool of LTC Benefits = $240,000/ Min. death advantage = $120,000 Cost: $3,555 Rates above consist of.
Determined: July 2026 Customers interested in discovering more about linked benefit long-term care insurance plan that consist of a development alternative so that advantages increase with time must call the Association to determine a well-informed and independent LTC insurance professional who offers policies from numerous insurance coverage service providers. Here are 10 essential reasons according to the American Association for Long-Term Care Insurance that it pays to deal with an independent professional when going shopping for long-term care insurance coverage.

Latest Posts
Practical Planning for Long-Term Health in 2026

Navigating Variable Annuities for Seniors
Securing Retirement Assets With Serious Illness Plans